Get offer-ready
Build a realistic budget, organize income and down-payment documents, and understand the conditions that still apply after pre-approval.
First-time buyer guidanceRegina mortgage advice, built around your life
Whether you are buying your first home, moving, renewing or refinancing, get a practical plan that connects the numbers to what matters next.
Mortgage studio
Explore a scenario in under a minute. These estimates are educational—not a lending decision—but they make your consultation more productive.
Estimated payment
$2,240/ month
With less than 20% down, default-insurance costs may apply and are not included in this estimate.
Start My Pre-ApprovalEstimated purchase range
$536,000approx.
Uses a 39% housing-cost and 44% total-debt starting point. Credit, insurer rules, condo fees, income type and lender policy can change the result.
Start My Pre-ApprovalCalculator estimates use Canadian mortgage compounding conventions and exclude default-insurance premiums, legal fees and other closing costs. Rates and qualification rules change. A broker must review your full application.
Straight answers, local context
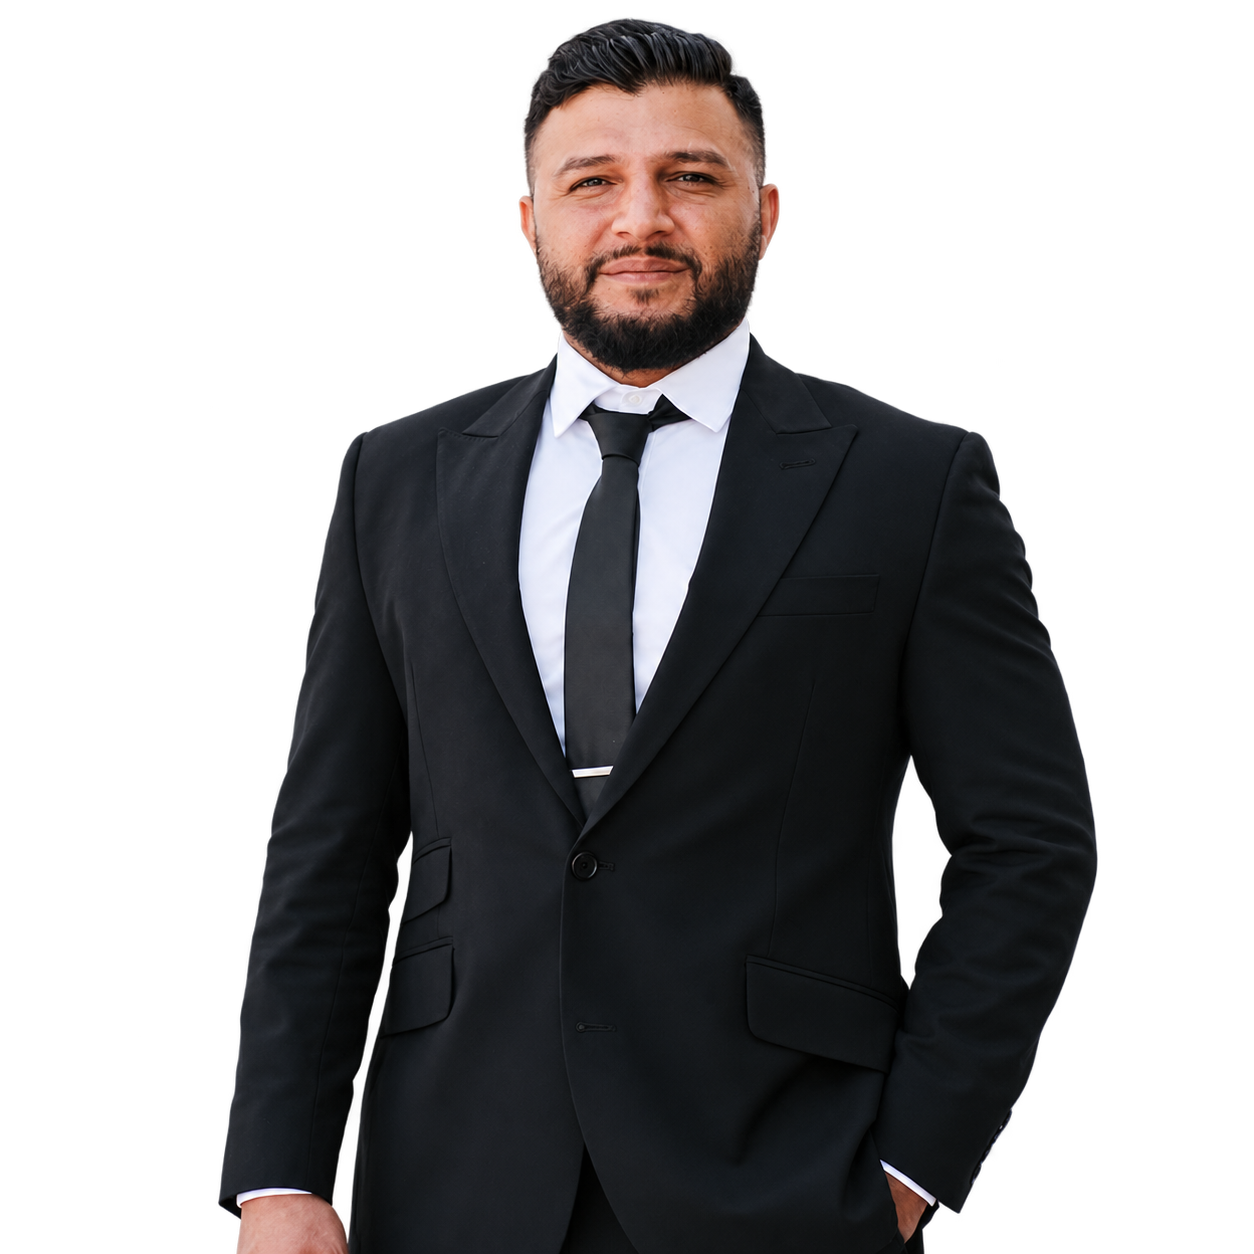
Ramin helps Saskatchewan clients compare the complete mortgage—not just the advertised rate—so penalties, flexibility, qualification and future plans all have a seat at the table.
Build a realistic budget, organize income and down-payment documents, and understand the conditions that still apply after pre-approval.
First-time buyer guidanceCompare rate, penalty, portability, prepayment privileges and cash-flow impact before signing a renewal or accessing equity.
Compare renewal optionsEligible buyers may combine an FHSA with the Home Buyers’ Plan. Program limits, timing and tax rules matter, so plan withdrawals before making an offer.
Follow the buying processIt depends on verified income, down payment, property costs, debts, credit and the qualifying rate. A useful first estimate compares housing costs near 39% of gross income with total debts near 44%, but lenders and insurers can use different limits.
For an eligible owner-occupied purchase under $1.5 million, it generally starts at 5% of the first $500,000 and 10% of the portion above that. At $1.5 million or more, at least 20% is generally required. Eligibility and insurer rules apply.
No. It helps set a budget and may hold a rate, but final approval still depends on verified documents, the property, lender conditions and no material change to your finances.
Review the offer first. A lower rate can be offset by a restrictive penalty, limited portability or weak prepayment options. Your next few years matter as much as the rate.
An FHSA can offer eligible first-time buyers tax-deductible contributions and tax-free qualifying withdrawals. The Home Buyers’ Plan can allow an eligible RRSP withdrawal. Limits and repayment rules change, so confirm the current rules before acting.
Client experience
“Ramin was very knowledgeable and helped me through the process of buying my first house. He was always available to answer my questions.”
“Very communicative and organized. He made the process easy and eliminated a lot of stress in buying a house.”
“He offers different solutions adapted to your needs and goes above and beyond. I will work with him again.”
Your next step
A focused conversation can help you see the trade-offs, avoid costly assumptions and decide what to do next.
Start My Pre-Approval